Proudly Serving Katy, Richmond & Fulshear Cinco Ranch
(281) 395-2100
|
(281) 394-4001

Dental insurance coverage typically pays for preventive care (cleanings, X-rays) at 100%, basic procedures (fillings) at 70–80%, and major work (crowns, root canals) at 50%, subject to an annual maximum—usually $1,000–$2,000. Most plans impose waiting periods of 6–12 months on major services and exclude cosmetic procedures entirely. Knowing your plan type, deductible, and network before you need care is what separates a manageable dental bill from a surprise one.
Understand What Dental Insurance Coverage Actually Includes
Dental insurance coverage splits benefits into three tiers, preventive, basic, and major, each reimbursed at a different rate.
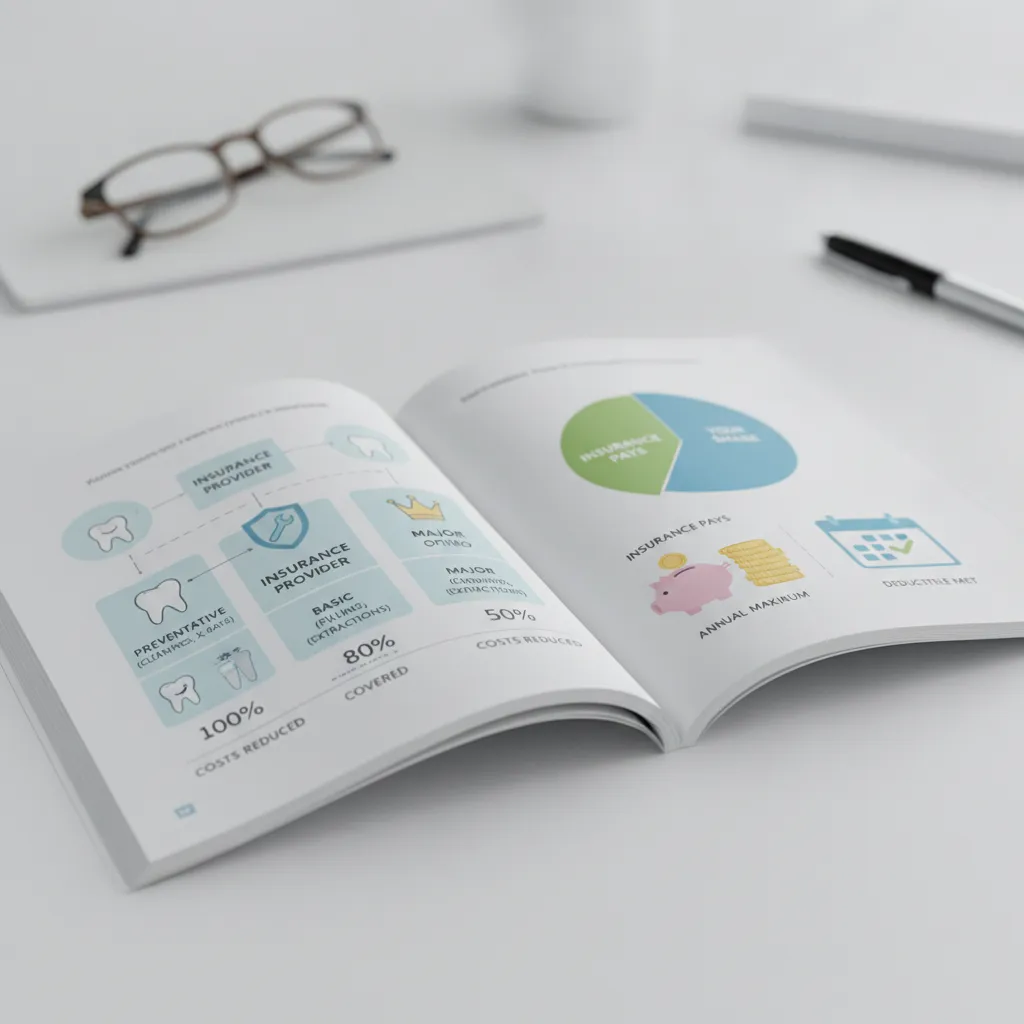
Most plans follow the 100-80-50 rule: preventive care at 100%, basic restorative work (like fillings) at 70–80%, and major procedures at 50%. On a $200 filling, your plan pays roughly $160 and you cover $40. On a $1,500 crown, your plan pays $750, and you owe the other $750 out of pocket, before factoring in your deductible.
Every plan also carries an annual benefit maximum, typically between $1,000 and $2,000 per person. Once you hit that ceiling, you pay 100% of any remaining dental costs for the rest of the calendar year, a detail many patients discover only after their second major procedure in 12 months.
“Preventive dental care is the single most cost-effective benefit in any dental plan. Patients who use their two annual cleanings consistently avoid the majority of major restorative costs over a lifetime.” — Dr. Matthew Messina, Consumer Advisor, American Dental Association
Does Any Dental Insurance Cover 100% of Dental Costs?
No plan covers everything at 100%, but preventive services come close. Two cleanings per year, bitewing X-rays, and fluoride treatments are covered at 100% on most plans, at no additional cost beyond your monthly premium. These benefits reset every year, yet a large share of enrollees never use them. That’s money left on the table.
One distinction worth making: dental insurance is not the same as a dental discount plan. Insurance involves a monthly premium, a deductible, and a carrier that shares financial risk with you. A discount plan charges a membership fee and gives you negotiated rates, but the insurer pays nothing. You pay the discounted rate yourself, in full, every time.
What Services Are Typically Excluded from Dental Insurance Plans?
Three categories are excluded on most base plans: cosmetic procedures (teeth whitening, veneers), adult orthodontics unless you add a rider, and dental implants. Implant exclusions are especially common, many carriers classify implants as cosmetic or elective, even when tooth loss is medically documented.
According to the American Dental Association, understanding your plan’s exclusions before treatment begins is one of the most important steps patients can take to avoid unexpected out-of-pocket costs.
At Villagio Family & Cosmetic Dental, our team reviews your specific plan before treatment begins, so you know exactly what your carrier will and won’t cover, no surprises at checkout.
Compare HMO, PPO, and Indemnity Dental Plan Types
Dental HMOs cost the least upfront, PPOs offer the widest network flexibility, and indemnity plans give you total provider freedom at the highest premium.
Choosing the right dental insurance coverage structure depends on how much provider choice matters to you versus how much you want to spend monthly. Each plan type trades one benefit for another.
| Plan Type | Monthly Premium (Individual) | Deductible | Network Flexibility | Major Procedure Reimbursement |
|---|---|---|---|---|
| HMO | $10–$25 | None | In-network only | Fixed copay; no out-of-network benefit |
| PPO | $20–$60 | $50–$150 per person | In- and out-of-network | 50% major; in-network pays 20–30% more than out-of-network |
| Indemnity | $40–$100+ | $50–$100 | Any licensed dentist | Set % of ‘usual and customary’ fees |
Dental HMOs carry the lowest premiums, typically $10–$25 per month for an individual, and require no deductible. The trade-off is strict: you must choose a primary care dentist from the plan’s network, and out-of-network visits receive zero reimbursement. This structure suits cost-conscious patients who don’t have a long-standing dentist relationship. For more information, see Brush Between Interdental Brush.
Dental PPOs are the most common employer-sponsored option. In-network reimbursement averages 20–30% higher than out-of-network rates, and annual deductibles run $50–$150 per person. At Villagio Family & Cosmetic Dental in Katy, TX, the majority of patients presenting employer plans carry PPO coverage, which means staying in-network directly reduces what you pay at the chair. For a broad overview of available PPO options, Delta Dental’s plan comparison tools can help you benchmark coverage levels and network size in your area.
Indemnity (fee-for-service) plans impose no network restrictions. The carrier reimburses a set percentage of ‘usual and customary’ fees regardless of which dentist you visit. That freedom comes with the highest premiums in the category, often $40–$100 or more per month, and reimbursement disputes are more common because ‘usual and customary’ benchmarks vary by carrier and ZIP code.
“The most common mistake consumers make when selecting a dental plan is focusing exclusively on the monthly premium. The annual maximum and coinsurance percentages for major procedures are far more predictive of your true annual cost.” — Dr. Paul Vining, Former President, National Association of Dental Plans
How Do Out-of-Pocket Maximums and Annual Deductibles Vary Across Major Carriers?
PPO and indemnity dental plans rarely cap total patient spending the way medical plans do, there is no federally mandated out-of-pocket maximum for dental coverage, unlike the ACA rules that govern health insurance [2]. Once you exhaust your annual benefit maximum (commonly $1,000–$2,000), you pay 100% of remaining costs for the rest of the plan year. Deductibles on PPO plans typically reset each January 1, so timing larger procedures, like a crown or extraction, just after the reset can cost you a second deductible within months.
Know the Costs, Waiting Periods, and Exclusions Before You Enroll
Most dental insurance coverage surprises happen before your first claim, waiting periods, exclusions, and cost gaps that weren’t obvious at sign-up.
What Waiting Periods and Pre-Existing Condition Exclusions Should You Expect?
Waiting periods vary by service tier. Preventive care, cleanings, X-rays, exams, typically carries no waiting period. Basic restorative work such as fillings usually requires 3–6 months of active coverage. Major procedures like crowns, bridges, and dentures often require 6–12 months on individual market plans. Employer-sponsored plans frequently waive these periods entirely, which is a meaningful advantage if you need care soon after enrollment.
Pre-existing condition exclusions are a critical difference from medical insurance. Unlike health plans governed by the ACA, dental plans can, and routinely do, exclude conditions that existed before your coverage started. The missing tooth clause is the most common trap: if you lost a tooth before your policy began, your plan may refuse to cover an implant or bridge to replace it. Read the exclusions section of any plan document before you enroll, not after a claim is denied.
At Villagio Family & Cosmetic Dental in Katy, TX, our team reviews your specific plan details with you before treatment begins, so you know exactly what your policy covers and where out-of-pocket costs will apply.
How Do Standalone Dental Plans Compare to Employer-Sponsored Coverage in Cost and Benefits?
Standalone individual dental plans average $20–$50 per month for adults. Employer-sponsored plans average only $14 per month in employee contributions, but that figure reflects $1,000–$2,000 in employer subsidy behind it. When your employer offers dental benefits, take them; the cost-benefit math rarely favors the individual market.
According to HealthCare.gov’s dental coverage guidance, Marketplace dental plans come in two tiers, low and high, and can be purchased as standalone plans or embedded within a health plan [2]. Pediatric dental is an ACA essential health benefit; adult dental is not [2]. One rule catches many enrollees off guard: you can cancel a standalone Marketplace dental plan without losing your health coverage, but you cannot drop embedded pediatric dental from a Marketplace health plan mid-year [2].
Avoid Common Dental Coverage Mistakes That Cost You Money
Five specific errors account for most of the money patients lose each year on dental insurance coverage, and every one is preventable.
- Not using preventive benefits. Most plans cover two cleanings per year at 100%, no deductible, no copay. Patients who skip those visits forfeit care they’ve already paid for through their premiums, and they miss the early catches that keep small problems out of the major-procedure tier. A cavity caught at a cleaning costs far less than a crown scheduled six months later.
- Assuming your dentist is in-network without verifying. Carrier directories are frequently outdated. Before your appointment, call the dental office directly, not the carrier’s website, and confirm your specific plan name and group number. At Villagio Family & Cosmetic Dental, the front desk team verifies insurance details before your visit so there are no billing surprises.
- Timing major procedures without checking your benefit year reset. Most annual maximums reset January 1. Scheduling a crown in late December instead of early January can mean the difference between 50% coverage and paying the full fee out of pocket, because your maximum is already depleted.
- Ignoring coordination of benefits when you carry two plans. If you hold coverage through your own employer and your spouse’s, submitting claims to both carriers, in the correct primary-then-secondary order, can cut your out-of-pocket costs significantly. Missing this step means leaving money on the table every claim cycle.
- Choosing a plan on premium alone. A $15/month HMO with a $1,500 annual maximum can cost more than a $40/month PPO if you need a crown and two fillings in a single year. Calculate total cost of ownership, premium plus likely out-of-pocket share, before enrolling.
Find In-Network Dentists and Estimate Your Real Costs Before Treatment
Confirming network status and requesting a predetermination before any major procedure are the two steps that prevent surprise bills under dental insurance coverage.
- Use your carrier’s provider directory filtered by your exact plan name. Delta Dental, Cigna, Aetna, and Guardian all offer searchable online directories, but the plan name matters. A dentist listed under “Delta Dental PPO” may not participate in “Delta Dental Premier,” and those are different fee schedules. Always call the dental office directly to confirm active participation before booking. Staff changes and contract renewals happen mid-year, and online directories lag behind.
- Request a pre-treatment estimate (predetermination) before any major procedure. Submit the dentist’s proposed treatment plan to your carrier before work begins. Carriers are required to respond within 30 days, and in most states the estimate is binding for the remainder of the plan year. At Villagio Family & Cosmetic Dental, the front office team routinely submits predeterminations on patients’ behalf so there are no cost surprises before a crown, bridge, or implant procedure.
- Benchmark procedure fees using carrier cost estimator tools. Delta Dental’s Cost Estimator and Cigna’s Dental Cost Tool both return typical procedure fees by ZIP code. If your dentist’s fee exceeds the “usual and customary” rate for your area, your plan reimburses only the lower benchmark figure, and you pay the difference out of pocket.
- Evaluate network size for your region before selecting a plan. Urban markets typically see 80% or more of dentists participating in major PPO networks; rural areas can fall below 40%. If you live outside a metro area, network adequacy should rank above premium cost when comparing plans.
- Start with your preferred dentist, not the plan. Ask the office which plans they accept, then compare those specific plans on annual maximum, waiting periods, and major-procedure reimbursement percentages. Working backward from a plan you’ve already purchased often means discovering your dentist is out-of-network after the fact.
How Do You Use Cost Estimators and Dental Plan Tools to Compare Expenses?
Pull up the cost estimator for each carrier you’re considering and enter your ZIP code alongside the procedure code your dentist has quoted. The tool returns the plan’s allowed amount, the ceiling it will reimburse. Subtract your coinsurance percentage from that figure to see your estimated share. Run the same calculation for two or three plans side by side, factoring in each plan’s annual maximum and any waiting period that applies to the procedure. That comparison gives you a dollar-level view of each plan’s real value before you enroll.
“Consumers who request a predetermination of benefits before major dental procedures are significantly less likely to face unexpected bills. It’s a simple step that most patients don’t know they can take.” — Dr. Marko Vujicic, Chief Economist and Vice President, Health Policy Institute, American Dental Association
Frequently Asked Questions
What insurance companies have the best dental coverage options?
Delta Dental, Cigna, Aetna, and Guardian consistently rank among the strongest carriers for dental coverage breadth and network size. Delta Dental is the nation’s largest dental insurer [1], with the widest provider network across the US. The best choice depends on your specific needs, whether you prioritize a low premium, a high annual maximum, or access to a particular dentist. At Villagio Family & Cosmetic Dental, we work with most major carriers and can confirm your benefits before your first appointment.
Can you cancel Marketplace dental coverage while keeping your health insurance?
Yes, you can cancel a separate Marketplace dental plan without affecting your health coverage [2]. The two plans are billed independently, so dropping dental does not trigger any change to your medical benefits. However, if your dental coverage is bundled inside a health plan rather than purchased as a standalone plan, you cannot remove just the dental portion [2]. For full details on how standalone and embedded dental plans work, review the dental coverage guidance on HealthCare.gov.
How do out-of-pocket maximums work differently in dental vs. medical insurance?
Most dental plans cap annual benefits at $1,000–$2,000 per year, the opposite logic of medical insurance, where the out-of-pocket maximum limits what you pay. In dental coverage, the annual maximum limits what the insurer pays; once that ceiling is reached, you cover 100% of remaining costs. Medical plans typically set out-of-pocket maximums between $7,000 and $9,000 for individuals, protecting you from catastrophic expense in a way most dental plans do not.
Does dental insurance cover implants?
Dental insurance rarely covers implants fully, most plans classify them as a major restorative procedure and pay 50% at most, subject to the annual maximum and any waiting period. Some plans exclude implants entirely. If your plan does include implant coverage, confirm whether it covers only the implant crown or also the post and abutment, since those components are often billed separately.
Is dental insurance worth it if you only need routine care?
For patients who need only two cleanings and annual X-rays, the math is close. Most preventive-only patients pay $20–$50 per month in premiums, which totals $240–$600 annually, often near the cost of two uninsured cleanings. The real value of dental insurance coverage emerges when an unexpected filling, extraction, or crown arises. Having active coverage when that happens, rather than enrolling after the fact and waiting out a 6–12 month waiting period, is the strongest argument for maintaining continuous coverage even in low-need years.
Conclusion
Getting the most from dental insurance coverage comes down to three practical moves: know your plan’s annual maximum before scheduling major work, confirm your dentist is in-network before every appointment, and time large procedures, like crowns or implants, across two calendar years to reset your benefits.
If you’re unsure what your current plan actually covers, the clearest next step is to call Villagio Family & Cosmetic Dental at our Katy, TX office before booking. Our team will verify your benefits directly with your carrier and walk you through exactly what you’ll owe, before you sit in the chair.
Sources & References
- Affordable Dental Insurance Plans | Delta Dental
- Dental Coverage in the Health Insurance Marketplace® | HealthCare.gov
- American Dental Association — Policy and Advocacy Resources
Recommended Articles
Explore more from our content library:
- A Complete Guide to Cosmetic Smile Improvements
- <a href="https://villagiofamilydental.com/blog/2026/08/07/how-to-find-a-family-dentist-you-can-trust-in-your-area/" title="How to Find a Family Dentist You Can Trust in Your Area”>How to Find a Family Dentist You Can Trust in Your Area
- A Complete Guide to Proper Flossing Technique
- A Complete Guide to Home Teeth Whitening Safely
- How to Manage Tooth Pain Until You Can See a Dentist